
Financial Independence and Empowerment for Older Women
Financial independence is a vital aspect of empowerment for older women, allowing them to live with dignity, confidence, and freedom. As women age, having control over personal finances becomes increasingly important for maintaining independence and making informed life decisions. Whether through savings, pensions, investments, or continued work, financial stability provides security and peace of mind. It also enables women to pursue their passions, support their families, and handle unexpected challenges without relying heavily on others. Understanding financial independence is the first step toward building a secure and fulfilling future.
The Importance of Financial Planning
Planning finances effectively is essential for long-term stability. Older women benefit from creating clear financial goals, tracking expenses, and managing income wisely. Financial planning includes budgeting, saving for emergencies, and preparing for retirement needs. It is important to review financial plans regularly and adjust them based on changing circumstances. With proper planning, women can avoid financial stress and ensure they have sufficient resources for healthcare, daily living, and personal goals.
Retirement Savings and Security
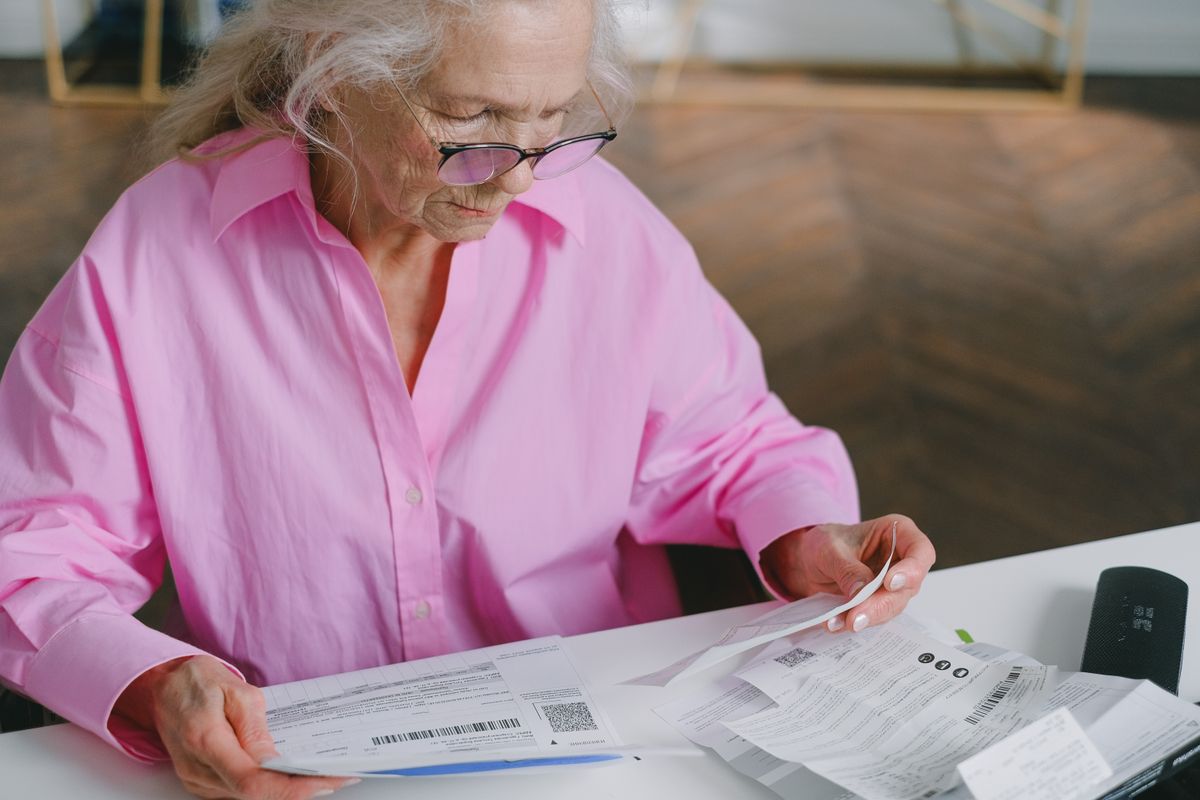
Retirement is a significant phase that requires careful financial preparation. Older women should focus on building and maintaining retirement savings through pensions, savings accounts, or investment plans. Understanding available options and making informed decisions can help ensure a stable income after retirement. Financial security during this stage allows women to enjoy life without constant financial worries. It also provides the freedom to travel, engage in hobbies, or spend quality time with loved ones.
Managing Expenses and Budgeting
Budgeting is a key skill that helps older women maintain control over their finances. By tracking income and expenses, they can identify areas where they can save and allocate resources more effectively. Managing daily expenses, reducing unnecessary spending, and prioritizing essential needs contribute to financial stability. A well-structured budget ensures that women can meet their financial obligations while still enjoying a comfortable lifestyle.
Investment and Wealth Growth
Investing is an important way to grow wealth and secure the future. Older women can explore safe and suitable investment options such as bonds, mutual funds, or low-risk portfolios. It is important to seek professional advice when needed and understand the risks involved. Smart investments can provide additional income and help maintain financial independence. Even small investments, when managed wisely, can contribute to long-term financial security.
Overcoming Financial Challenges
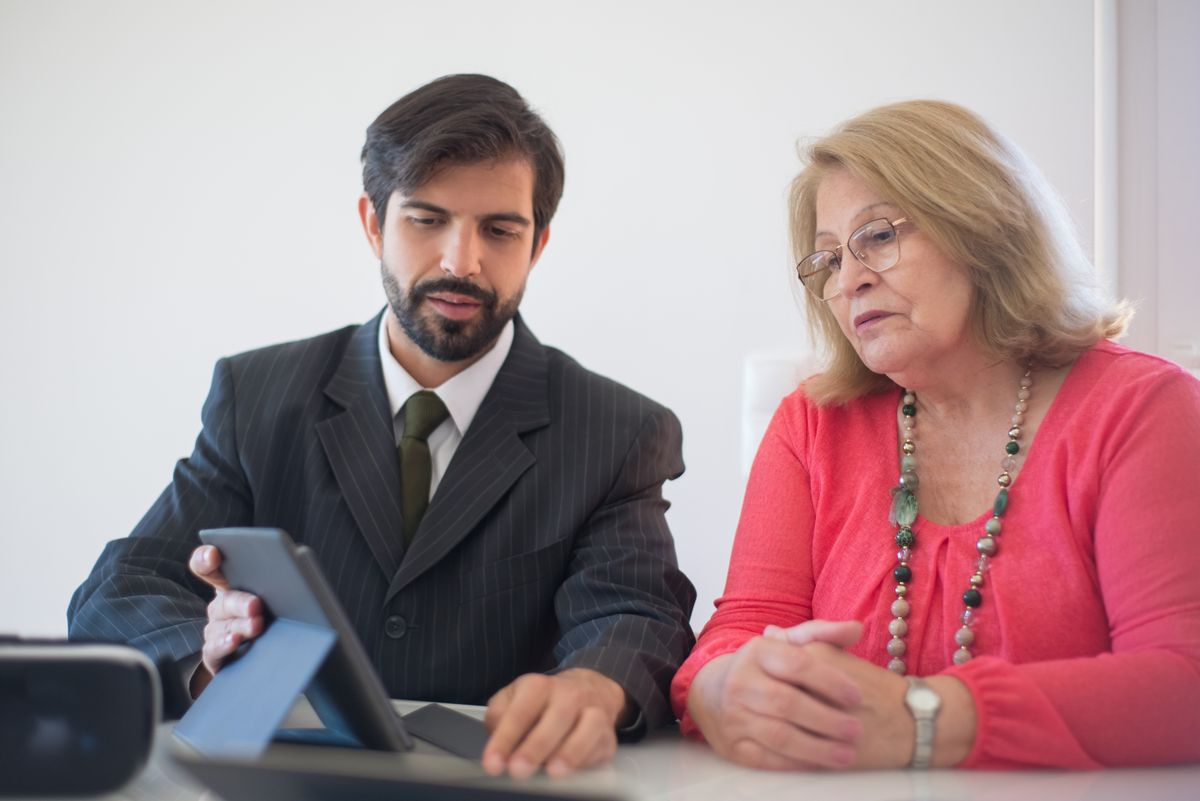
Many older women face financial challenges due to career breaks, lower lifetime earnings, or unexpected life events. However, resilience and determination can help overcome these obstacles. Seeking financial education, exploring income opportunities, and making informed decisions are crucial steps. Support from financial advisors or community programs can also be beneficial. Facing challenges with a proactive mindset allows women to regain control and build a stable future.
Social Security and Government Benefits
Understanding government benefits is a critical piece of the financial picture for older women, yet it’s often the most confusing. Social Security (or the equivalent state pension system, depending on the country) rewards delayed claiming — waiting even a few extra years past the earliest eligible age can meaningfully increase the monthly benefit for the rest of a woman’s life. Because women statistically live longer than men, this compounding effect matters more for them, not less. Spousal and survivor benefits add another layer of complexity, and many women leave money on the table simply because they never sat down to compare all their claiming options side by side. A single consultation with a benefits counselor or a few hours of independent research can permanently change the size of a monthly check.
Estate Planning and Leaving a Legacy
Estate planning is frequently postponed because it feels uncomfortable to think about, but having a will, a designated power of attorney, and clear beneficiary designations is one of the most protective things an older woman can do for herself and her family. Without these documents in place, decisions about assets, healthcare, and property can end up in the hands of courts or distant relatives rather than the people a woman would have actually chosen. Beyond the legal mechanics, estate planning is also an opportunity to think intentionally about legacy — what values, resources, or opportunities a woman wants to pass on, and to whom. Many women describe finishing their estate plan as one of the most liberating financial tasks they’ve ever completed, precisely because it removes a background worry they didn’t realize they were carrying.
Navigating Housing Decisions
Housing is usually the largest asset and the largest expense in an older woman’s budget, which makes housing decisions inseparable from financial independence. Some women choose to stay in a long-time family home, weighing the emotional value of familiarity against the practical costs of maintenance and property taxes. Others downsize deliberately, freeing up equity that can fund retirement, travel, or a more accessible living situation as mobility needs change. Multigenerational living and co-housing arrangements with friends have also grown more common, offering both financial relief and built-in companionship. There’s no single right answer — the healthiest approach treats housing as a financial decision to revisit periodically, not a choice made once and never reconsidered.
Health Insurance and Planning for Medical Costs
Healthcare costs tend to rise with age, and they are one of the most common reasons retirement savings run short. Understanding what is and isn’t covered by public health programs, and where supplemental insurance may be worth the premium, prevents unpleasant surprises later. Setting aside a dedicated health savings fund, separate from general retirement savings, gives women a buffer for costs that insurance doesn’t fully cover — dental work, vision care, or long-term care needs, for example. Being proactive here isn’t pessimism; it’s simply extending the same planning mindset that applies to housing or retirement income to the one category of spending that is hardest to predict.
Working With a Financial Advisor
A good financial advisor can be genuinely valuable, but knowing how to choose one matters. Fee-only advisors, who are paid a flat rate rather than a commission on the products they sell, tend to have fewer conflicts of interest when recommending investments. It’s reasonable — expected, even — to interview more than one advisor before committing, and to ask directly how they’re compensated. Women who have historically been talked over or steered in financial conversations should feel entitled to ask follow-up questions until an explanation actually makes sense, rather than nodding along. A good advisor welcomes that scrutiny; it’s often the clearest sign of a trustworthy one.
Building and Protecting an Emergency Fund
An emergency fund is the financial equivalent of a seatbelt — rarely needed on any given day, but the difference between a manageable setback and a genuine crisis when something does go wrong. Financial advisors commonly recommend three to six months of essential expenses set aside in an easily accessible account, though the right number varies with individual circumstances like health, housing stability, and other income sources. For many older women living on a fixed income, rebuilding this cushion after a major expense can feel slow, but even small, consistent contributions add up over time. The goal isn’t a specific dollar figure so much as the peace of mind that comes from knowing an unexpected bill won’t derail an otherwise stable plan.
Learning From Real Stories of Financial Independence
Some of the most useful financial education doesn’t come from textbooks but from hearing how other women actually navigated their own turning points — a late-life divorce that forced a full financial restart, a small side business that grew into a primary income source, or simply the decision to finally open a retirement account after years of putting it off. These stories matter because they replace abstract advice with proof that it’s genuinely possible to build stability at any stage, even starting later than ideal. Women who share their financial journeys openly — in community groups, online forums, or simply with friends — often find that the conversation itself is empowering, breaking a long-standing cultural discomfort around openly discussing money.
Diversifying Income Beyond a Single Source
Relying on a single source of income — one pension, one investment account, one part-time job — leaves less room to absorb a shock than a diversified approach does. Rental income from a spare room, dividends from a modest stock portfolio, royalties from creative work, or a small recurring freelance client can each seem minor on their own, but together they create a more resilient financial picture. This isn’t about chasing every possible income stream; it’s about not putting all of one’s financial security into a single basket that could disappear or shrink unexpectedly. Women who diversify their income report feeling less anxious about any one piece of their financial life going wrong, because no single disruption threatens everything at once.
Teaching Financial Literacy at Any Age
It’s a common misconception that financial literacy is something you either learned young or missed out on entirely. In reality, financial habits and knowledge can be built at any age, and many older women report feeling more capable of learning financial concepts later in life than they did decades earlier, simply because they have more patience and less pressure to get everything right immediately. Community centers, libraries, and online courses increasingly offer financial literacy programs specifically designed for older adults, covering everything from basic budgeting to understanding investment statements. Taking the first class or reading the first book is often the hardest part — after that, the learning tends to build naturally on itself.
Navigating Financial Decisions After Loss
The death of a spouse or partner often triggers major, urgent financial decisions at the exact moment a woman is least prepared to make them. Insurance claims, changes to household income, decisions about jointly-owned property, and adjustments to retirement benefits can all arrive within the same difficult weeks. Financial professionals who specialize in working with widows recommend avoiding major irreversible decisions — like selling a house or making large investment changes — in the first year after a loss, when emotions and unfamiliarity with the full financial picture can cloud judgment. Building a support team in advance, even informally, makes an enormous difference if this moment does arrive.
The Freedom That Comes With Financial Clarity
Beyond every individual strategy — budgeting, investing, planning for healthcare, protecting against scams — the underlying goal of financial independence is simple: the freedom to make life decisions based on what a woman actually wants, rather than what her bank balance forces her into. That freedom looks different for everyone. For some, it means being able to help a grandchild through school. For others, it’s the ability to leave a difficult living situation, take a long-postponed trip, or simply stop worrying every time an unexpected bill arrives. Financial independence isn’t about accumulating wealth for its own sake — it’s about removing money as a source of fear so that other parts of life can take center stage.
Setting Financial Goals for Every Stage
Financial goals shouldn’t be static — what makes sense at sixty rarely makes sense at eighty, and revisiting goals every year or two keeps a financial plan aligned with actual life circumstances rather than outdated assumptions. Short-term goals might include building a specific savings cushion or paying down a remaining debt, while longer-term goals often center on preserving independence, funding healthcare needs, or leaving a planned legacy. Writing goals down, even informally, makes them meaningfully more likely to be achieved than simply holding them as vague intentions. The exercise of setting and revisiting goals is itself a form of financial confidence-building, reinforcing that a woman is actively steering her own future rather than simply reacting to whatever happens next. Small, regular check-ins — a monthly ten-minute review of accounts and spending — tend to matter more over time than any single big decision.
The Role of Technology in Financial Management
Technology has made financial management more accessible and convenient. Older women can use online banking, mobile apps, and digital tools to track expenses, pay bills, and manage investments. Learning to use these technologies can simplify financial tasks and improve efficiency. While adapting to new tools may seem challenging at first, it offers greater control and flexibility in managing finances.
Building Financial Confidence
Financial confidence is about understanding and trusting one’s ability to manage money effectively. Older women can build confidence by educating themselves about financial matters, setting realistic goals, and making informed decisions. Confidence grows with experience and knowledge, empowering women to take charge of their financial future. This sense of control enhances overall well-being and independence.
Supporting Future Generations
Older women often play an important role in guiding younger generations about financial responsibility. By sharing their experiences and knowledge, they can help others avoid common mistakes and make better financial choices. Teaching children and grandchildren about saving, budgeting, and investing creates a legacy of financial awareness and stability. This contribution extends their impact beyond their own lives.
Starting a Business or Encore Career
More older women are choosing to launch a business or pivot into a new career later in life, often called an “encore career.” Decades of experience, an established network, and a clearer sense of purpose make this stage a genuinely strong time to start something new. Consulting, coaching, freelance work, and small e-commerce businesses are especially popular because they can start small and scale gradually, without requiring large upfront investment. An encore career adds income on top of savings or pension, which meaningfully strengthens financial independence rather than replacing it entirely.
Protecting Yourself From Financial Scams
Older women are unfortunately a frequent target for financial scams, from fake investment schemes to phone and email fraud designed to look official. Awareness is the strongest defense: legitimate banks and government agencies will never ask for passwords or one-time codes over the phone, and any offer that promises guaranteed high returns with no risk should be treated with suspicion. Taking a moment to verify a request independently — by calling the institution directly using a number you already know, not one provided in the suspicious message — stops the vast majority of scams before any money changes hands. Talking openly with family or a trusted advisor about unusual financial requests adds another layer of protection.
Financial Independence and Mental Well-Being
The connection between financial security and mental health is well documented, and it becomes especially pronounced later in life. Constant money worries contribute to anxiety and can affect sleep, relationships, and physical health. Women who have a clear handle on their finances report feeling calmer and more in control of their day-to-day lives. This isn’t about having unlimited wealth — it’s about knowing where you stand, having a plan, and trusting that plan. That sense of control is, in itself, one of the most valuable outcomes of financial independence.
Conclusion: Empowerment Through Financial Independence
Financial independence empowers older women to live life on their own terms. It provides security, confidence, and the freedom to pursue personal goals and interests. By focusing on financial planning, budgeting, and continuous learning, women can build a strong foundation for their future. Aging should be a time of empowerment and fulfillment, and financial independence plays a crucial role in achieving that.